Subcontractors vs In-House Crews for Pool Construction: Cost, Control, and Risk
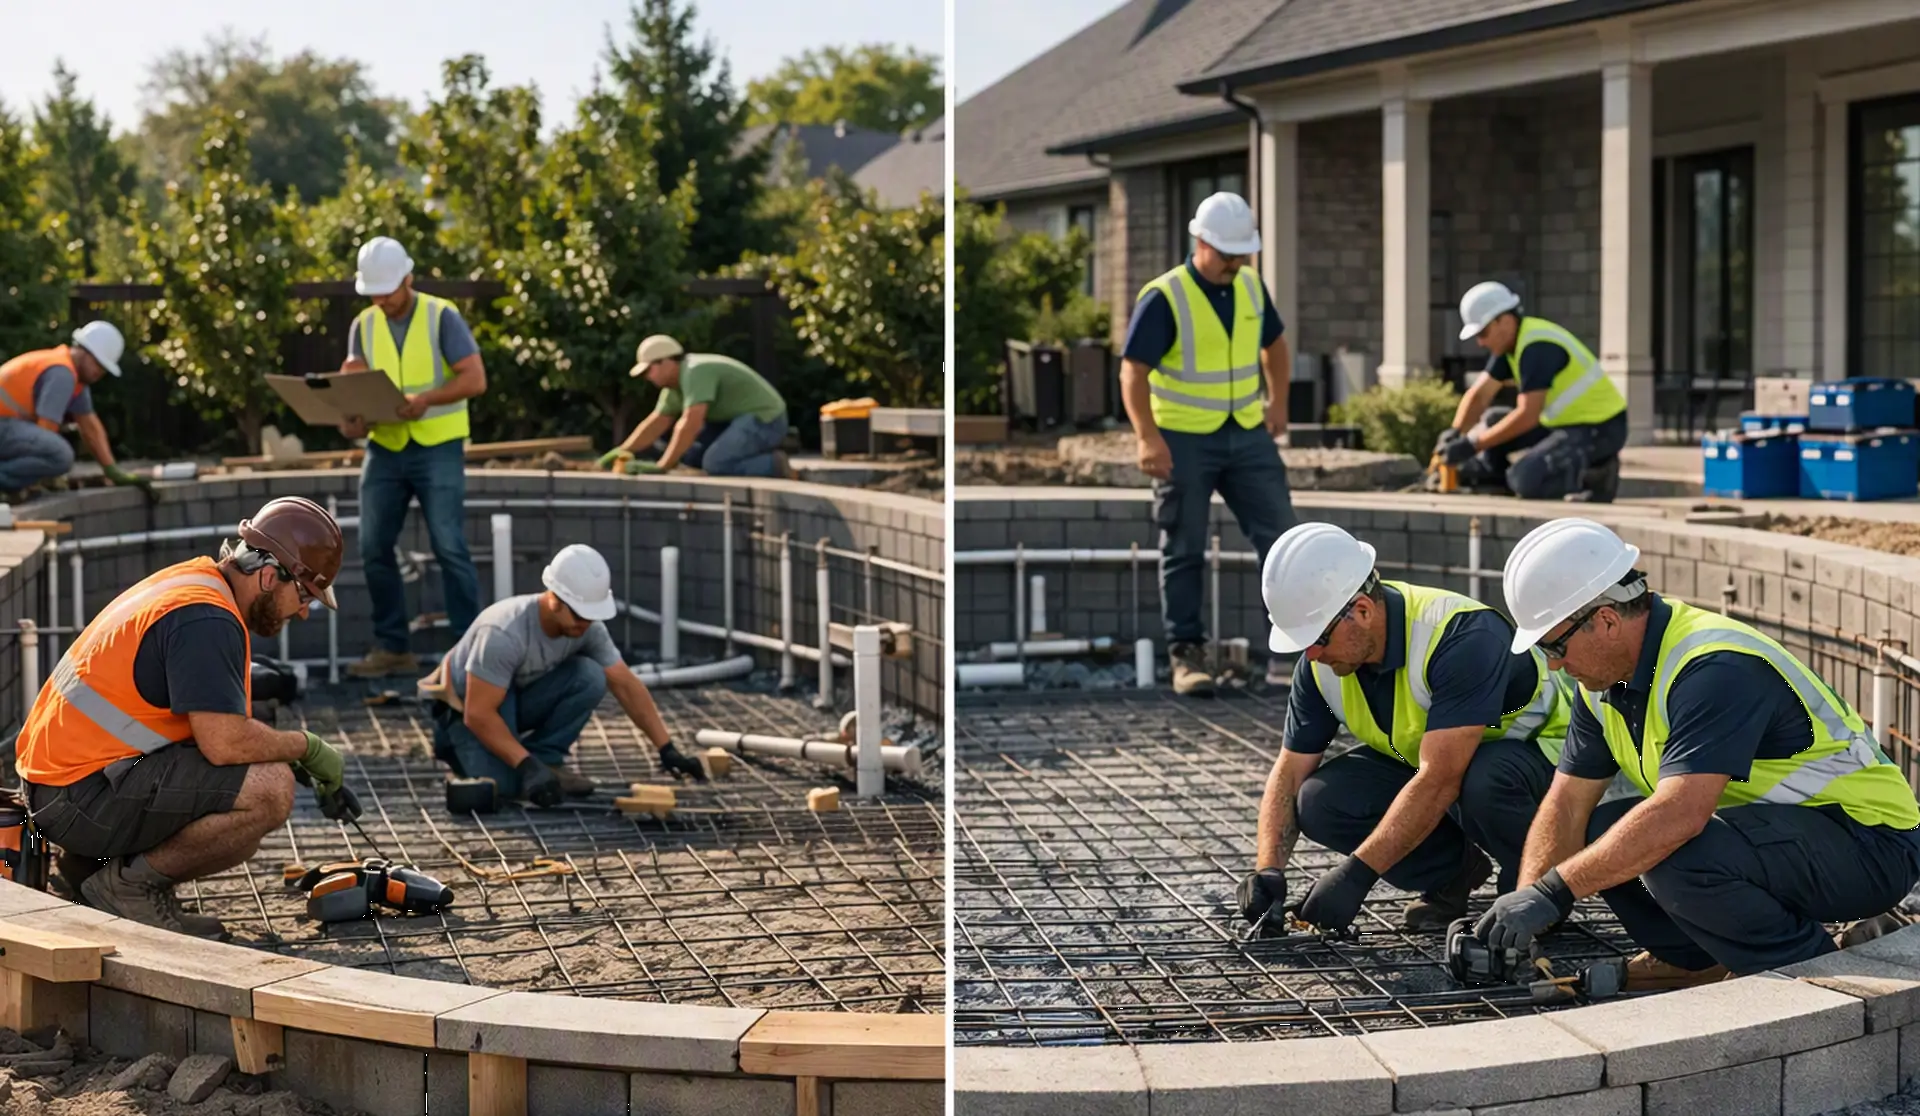
Table of Contents
Every swimming pool construction company faces the same staffing question at some point. Do you hire your own crews or subcontract the work? The answer shapes your margins, your schedule, your quality, and your liability exposure.
Most pool builders use some combination of both. Gunite spraying, electrical hookups, tile work, and plaster finishing are commonly subcontracted. Excavation, plumbing, and basic project management are often kept in-house. But where you draw that line determines how much control you have and how much risk you carry.
That risk piece is what most builders underestimate. Whether you use subs or employees, your specialty insurance needs to reflect how your swimming pool construction operation actually runs. A sub without proper coverage who gets hurt on your site becomes your problem. An in-house crew classified under the wrong workers’ comp code creates audit exposure at renewal.
Here’s how the two models compare across cost, control, and risk.
Key Takeaways
- Fully burdened in-house labor (payroll taxes, workers’ comp, benefits) typically runs 35-60% above base wage, even during slow months.
- Builders running fewer than 15 pools a year typically keep overhead low by subcontracting trades like gunite, electrical, and plaster.
- In-house crews reduce per-job costs once volume passes roughly 20-25 pools a year, but carry full payroll, benefits, and equipment costs through the off-season.
- Uninsured or lapsed subcontractor coverage is the most common risk gap: an injured, uninsured sub can still file a claim against the general contractor’s policy.
- Completed-operations coverage matters most for subcontracted trades, since claims like delaminated tile can surface months after the sub has moved on.
- Reviewing subcontractor agreements and certificates of insurance at least twice a year, with a specialty insurance provider like NIP Group, closes most of these gaps.
Cost Comparison: In-House vs Subcontractors
The cost difference between in-house crews and subcontractors isn’t just about the hourly rate. It’s about fixed versus variable overhead.
| Factor | In-House Crews | Subcontractors |
|---|---|---|
| Labor cost structure | Fixed payroll year-round | Variable, pay per project |
| Benefits and taxes | Employer pays health, comp, FICA | Sub handles their own |
| Equipment | Company owns and maintains | Sub brings their own |
| Insurance burden | Workers’ comp, GL on your payroll | Sub carries their own (verify) |
| Off-season cost | Full payroll during slow months | Zero cost when no work assigned |
| Per-job cost | Lower once crews are trained | Higher per job, lower overhead |
Industry benchmarks put this in dollar terms. These numbers below are national averages; actual rates shift a lot by region, trade, market conditions.
Fully burdened in-house labor, once you add payroll taxes, workers’ comp, and benefits, typically runs 35% to 60% above the base hourly wage, with workers’ comp alone adding anywhere from 5% to 25% depending on the trade (SmartBarrel).
On the subcontractor side, pool contractor labor commonly runs $35 to $75 an hour, with excavation crews ranging $40 to $180 an hour depending on site conditions. Labor alone typically makes up roughly a third of a gunite pool’s total installed cost, in the $5,000 to $30,000 range per pool on a project that averages around $100,000 overall (Angi).
In-house crews cost more when work slows down. You’re paying full-time wages, benefits, and equipment costs even during the off-season. But when your pipeline is full, in-house labor costs less per job because you’re not paying a sub’s markup.
Subcontractors eliminate fixed overhead. You pay only when there’s work. But you pay retail for their labor, and you have no volume leverage unless you’re feeding them consistent work.
Quick summary: In-house crews reduce per-job costs at high volume but increase fixed overhead. Subcontractors keep overhead low but cost more per project. Most swimming pool construction companies blend both models based on volume and trade specialty.
Control: Scheduling, Quality, and Customer Experience
Control is the main reason pool builders bring crews in-house. When your employees do the work, you set the schedule, the quality standards, and the customer interaction.
In-house crews give you:
- Direct scheduling control, with no waiting on a sub’s availability
- Consistent quality: same crew, same standards, same training
- Faster response time when issues come up on-site
- Better customer experience, since your crew represents your brand
Subcontractors introduce variables:
- Their schedule depends on their other clients, so your project may not be their priority
- Quality varies between subs, and between crews within the same sub
- Customer-facing interactions are harder to manage when the crew isn’t yours
- Accountability gets complicated when the homeowner sees different crews on-site each week
The worst scenario is depending on a sub who doesn’t prioritize your work. Smaller builders face this often: their subs also work for larger companies, and their projects get pushed back.
That said, subcontractors bring trade-specific expertise most builders can’t replicate in-house. A gunite crew that shoots pools full-time will outperform a general laborer you trained last month.
Risk: Where Swimming Pool Construction Companies Get It Wrong
This is where the sub vs in-house decision carries the most weight.
In-House Crew Risk
With employees, you carry workers’ comp, GL, and commercial auto directly. You control safety protocols, training, equipment, and OSHA compliance.
If an employee gets hurt, the claim is straightforward. Your workers’ comp responds and your EMR tracks the incident.
Subcontractor Risk
With subcontractors, the risk profile shifts, but not away from you. If a sub doesn’t carry adequate insurance and someone gets injured on your job site, the claim can fall back to your policy.
Common subcontractor risk gaps in swimming pool construction:
- Sub’s GL policy has lapsed or doesn’t cover pool work specifically
- Sub doesn’t carry workers’ comp, and their injured worker files against your policy
- Sub’s work fails after the project is complete, and the homeowner sues you as the general contractor
- Sub damages a neighbor’s property during excavation, and your GL gets pulled into the claim
Note
Verify every subcontractor’s insurance before they set foot on your site. Request current certificates of insurance. Confirm the policy is active, not just issued. Check that their coverage includes the specific trade they’re performing on your project.
The Completed Operations Gap
This one catches pool builders off guard. Your sub installs tile. Six months later it delaminates and the homeowner files a claim. The sub has moved on. Their policy may have lapsed.
As the GC, you’re the one the homeowner contacts. Your completed operations coverage needs to account for subcontracted work. Many standard policies limit this, and builders don’t realize it until the claim arrives.
Structuring Your Swimming Pool Construction Crew Model for Growth
The right mix depends on your volume, your market, and your risk tolerance.
Start with subcontractors if you’re building fewer than 15 pools per year. Keep overhead low and focus on sales and project management.
Bring trades in-house as volume grows past 20–25 pools per year. Start with the trade causing the most scheduling problems.
Keep specialized trades subcontracted unless volume justifies a full-time crew. Gunite, electrical, and plaster are typically more cost-effective as sub work.
Regardless of your model, providers like NIP Group build coverage for pool contractors that accounts for both in-house and subcontracted work. That distinction matters because your policy needs to cover claims from subs working on your behalf, not just your own employees.
Important
Review your subcontractor agreements and insurance certificates at least twice per year. A certificate issued in January may not reflect a policy change made in June.
FAQs
Most swimming pool construction companies use a blend of both. In-house crews work best for high-volume trades where scheduling and quality control matter most. Subcontractors make sense for specialized work like gunite, electrical, and plaster, where trade expertise outweighs the control benefit.
You need GL with completed operations coverage that extends to subcontracted work. You should also require every sub to carry their own GL and workers’ comp. Verify certificates before each project and confirm policies are active and cover pool-related work specifically.
Subcontractors cost more per project but eliminate fixed overhead like year-round payroll, benefits, and equipment maintenance. In-house crews reduce per-job costs at higher volumes but increase your baseline expenses. The break-even point for most pool builders sits around 20–25 projects per year.
If the sub doesn’t carry workers’ comp, the injured worker can file a claim against your policy. Even with proper sub insurance, you may face liability if your site conditions contributed to the injury. Always verify sub coverage and maintain safe site protocols.
Disclaimer: Coverage details, trade classifications, and insurance requirements mentioned in this article can vary by state, project type, and policy terms. Always confirm current coverage, certificate requirements, and policy terms directly with your insurance provider or broker before relying on them. This article is for informational purposes only and should not be considered legal, insurance, or risk-management advice.